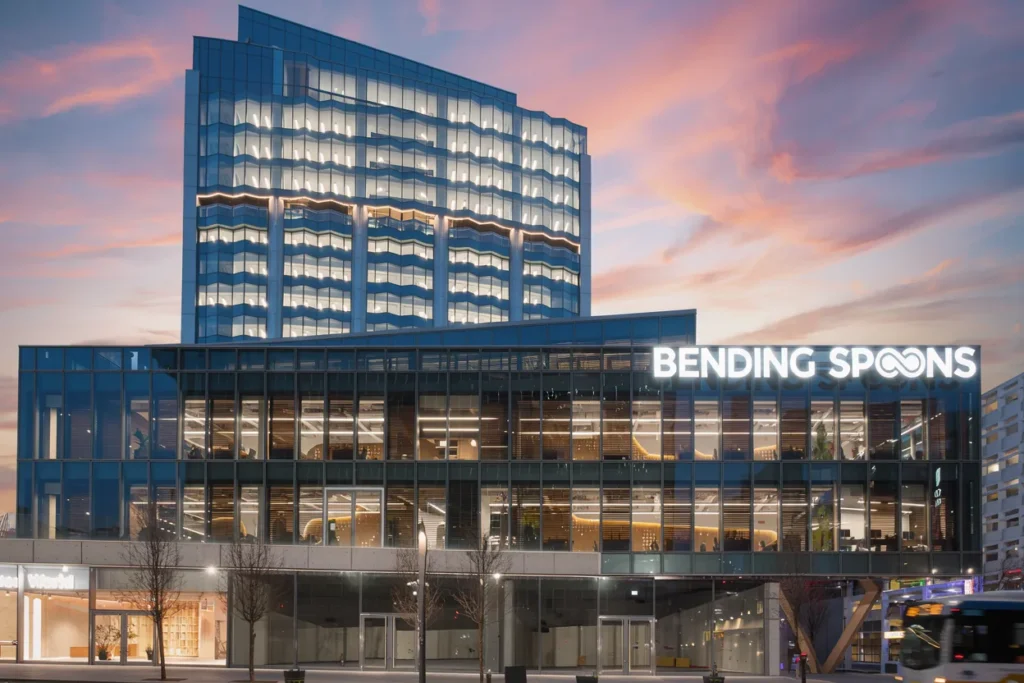
A familiar name changes hands at a very different price
Bending Spoons’ name may be less familiar than the products it owns. WeTransfer, Vimeo, Evernote and Eventbrite already sit inside the Milan-based company. Mailchimp could soon join them.
The $3.68 billion agreement with Intuit values the email marketing business at less than a third of the roughly $12 billion Intuit paid in 2021. Intuit will reinvest $368 million of the proceeds in newly issued Bending Spoons shares. Bending Spoons
That is a substantial change in expectations for a business once bought to help power small-business growth.
For Bending Spoons, the lower purchase price leaves more room to invest in a recovery. But Mailchimp’s problem needs more than a change of ownership: its latest results show customers leaving.
The collection is becoming an operating business of considerable scale
Bending Spoons has assembled products that handle familiar pieces of working life: sharing files, hosting videos, organizing events and managing workflows.
Its latest acquisitions broaden that reach. The company completed its $1.29 billion Airtable acquisition in September and acquired Miro for $1.36 billion in October. sec.gov
These are established products with existing customers. Bending Spoons’ approach is to buy them and apply its own engineering, product development and commercial expertise. Its operating model includes substantial changes to technology, interfaces and organizational structures. Bending Spoons
Mailchimp fits that pattern. It also brings the company closer to something nearly every business needs: a way to turn an audience into repeat customers.
As recognizable software brands move under this owner, WSA is following how the businesses perform after the acquisition announcements fade.
You Know the Brands. Get the Stock Stories Behind Them in Your Inbox.
Winning customers back starts with making the product worth staying for
Mailchimp generated $313 million in quarterly revenue, down 1%. Intuit attributed the decline to fewer paying customers and a shift in customer mix, partly offset by higher effective prices.
Cost reductions helped lift segment operating profit. That improves near-term earnings, but sustained growth requires a healthier customer base. Intuit Inc. (INTU)
The competition offers a useful comparison. Klaviyo’s third-quarter revenue increased 25% to $387.2 million. Its broader product mix makes this an imperfect comparison, but it shows that marketing software can still attract growing spending. investors.klaviyo.com
Mailchimp already offers AI tools, automation, SMS and hundreds of integrations. Simply adding another AI feature will have plenty of company. Mailchimp
A stronger competitive position would come from making those capabilities easier to use and their results easier to measure. A small business needs to understand which campaigns bring customers back—and whether the subscription earns its place in the budget.
Bending Spoons’ portfolio creates possibilities here. Smoother connections between events, video and email campaigns could reduce the work required to reach an audience. That is a potential direction, rather than an announced integration plan.
Leadership in email marketing would have to be earned through that everyday experience: useful automation, reliable delivery, responsive support and pricing customers can justify.
The acquisition engine still needs to prove its organic growth
Bending Spoons’ third-quarter revenue rose 125% to $780 million, primarily through acquisitions; organic revenue growth was 3%.
The difference matters. Buying businesses expands the revenue base immediately. Improving them enough to retain customers and grow sales takes longer.
Financing adds another consideration. The company reported $4 billion of net debt at September 30, before the Miro acquisition and proposed Mailchimp transaction. sec.gov
Bending Spoons remains a company WSA is following because it is bringing substantial software assets under one operating model, with multiple opportunities to improve products and commercial performance. The same pace of dealmaking raises the demands on integration and capital allocation.
Mailchimp provides a particularly clear test. The acquisition is expected to close in early 2027, subject to regulatory approval. After that, returning the business to growth will mean persuading more customers that a familiar platform deserves another look.
Disclaimer
Wall Street Access is an independent financial publisher. Wall Street Access is not a financial advisor. No company mentioned has compensated Wall Street Access for the preparation, publication or distribution of this article. This content is provided for informational and educational purposes only and is not investment advice or a recommendation to buy, sell or hold any security. Investing involves risk, including the possible loss of principal.
Prices, market capitalizations, financial figures and other market data are based on information available as of the date and time of publication and may change without notice. Information is drawn from public sources believed to be reliable but is not guaranteed to be complete or accurate. Opinions and expectations expressed are our own and may change as new information becomes available.
Readers should conduct their own due diligence and contact a licensed financial professional before making any investment decision. Past performance does not guarantee future results. Any material ownership interest or conflict of interest, where applicable, will be disclosed separately.